Transition to retirement
Work less, save more – here's how
How it works
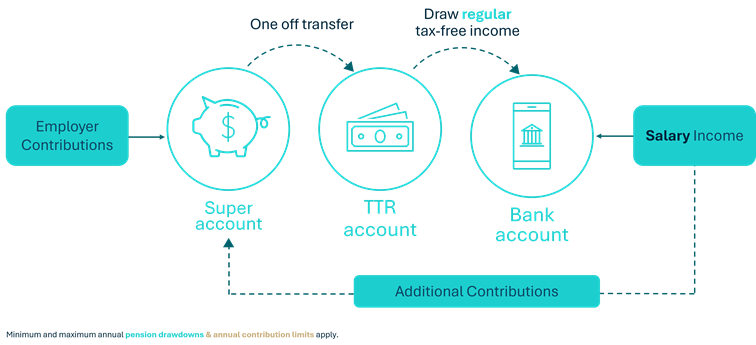
If you’re eligible, you can open a TTR account and transfer some of your super to your new TTR account.
It’s important to keep your super account open so you can still receive contributions from your employer and yourself. And keep your insurance cover active.
You can then draw an income of between 4 and 10% of your TTR balance to be paid into your bank account to top up your income.
Transition to retirement strategies
Depending on your goals, there are two main ways you can use a TTR account:
1. Save on tax while growing your super
2. Reduce your work hours and maintain your income
Save on tax while growing your super
How it works
-
Make extra concessional contributions (for example through salary sacrifice) into your PSSap account
-
Draw a regular income from your TTR account.
-
Concessional (before-tax) contributions are generally taxed at 15%, which may be lower than your marginal tax rate.
-
Your employer continues paying compulsory super contributions to your PSSap account.
Benefits
- Reduce taxable income.
- Keep growing your super while you work.
- Receive a regular income stream.
Considerations
Talk to a specialist or seek advice
Consider talking to a CSC Super Specialist (at no additional cost to you) for general information or seek financial advice to understand if this strategy is right for you.
Contribution caps
Contribution caps apply to both before and after-tax contributions.
Find out more on the ATO website
Case study
Alex funded his surfing safari with the money he saves on tax using his TTR
Alex, aged 60, earns $100,000 a year (taxable income) and has $400,000 in super. Alex wants to keep working full-time but is looking for ways to reduce tax and continue to grow his super while he’s still working.
- Alex opens a CSCri Transition to retirement (TTR) income stream with a starting account balance of $200,000 and starts receiving regular payments from his TTR account of $10,000 annually.
- He salary sacrifices $10,000 into his PSSap super account, reducing his taxable income to $90,000. Salary sacrifice contributions are considered ‘concessional contributions’ by the ATO and are taxed at just 15%, which is lower than Alex’s marginal tax rate.
How does this help save on tax?
By using a TTR strategy Alex reduces his taxable income from $100,000 to $90,000.
- Without TTR: Alex pays approximately $22,788 in tax.
- With TTR: Alex pays around $21,088 in total tax—$19,588 on the reduced salary and $1,500 on the super contributions (taxed at 15%).
That’s a tax saving of $1,700 for the year. This is done by changing how his income is received - he contributes part of his income to super and then receives that income through a TTR income stream.
Not only does Alex save on tax, he also continues to grow his super because his employer is still paying compulsory super contributions to his PSSap account while he works.
How the numbers add up
| Taxable income | Income tax rate | Income tax paid | Salary sacrifice contribution | Super tax rate | Overall tax paid | Total tax paid | |
|---|---|---|---|---|---|---|---|
| Without TTR | $100,000 | Marginal rates | $22,788 | $0 | N/A | 22.79% | $22,788 |
| With TTR | $90,000 | Marginal rates | $19,588 | $10,000 | 15% | 21.09% | $21,088 |
| Total tax saving | $1,700 | ||||||
Note: Figures are illustrative only and do not account for offsets or personal circumstances. Income tax includes the Medicare levy of 2%.
By using a TTR strategy:
- Alex saves $1,700 in tax annually.
- His super continues to grow with contributions from his employer while he keeps working.
Alex puts his saving towards a well-deserved surfing safari.
This case study is for illustrative purposes only and does not constitute financial advice. Individual circumstances vary. Consider seeking professional advice before making any decisions.
Reduce work hours and maintain income
If you're ready to reduce your work hours, a TTR strategy can help you do this while maintaining your income.
How it works
-
Reduce your work hours and use TTR payments (of up to 10%, of your account balance) to top up your income.
-
For people aged 60 and up to 64, TTR income payments are tax-free.
-
Employer contributions continue to be made to your PSSap account (based on your reduced salary).
Benefits
- Enjoy more time doing the things you love while maintaining your take-home pay.
- Continue receiving employer super contributions.
Considerations
Super savings
Drawing from your super early may leave you with less money when you retire fully.
Talk to a specialist or seek advice
You may want to talk to a CSC Super Specialist (at no additional cost to you) for general information or seek financial advice to understand if this strategy is right for you.
Case study
Sam moved to a four-day week while keeping the same income, freeing up time to grow her Youtube channel
Sam, aged 60, earns $100,000 (taxable income) annually and is working five days a week. She has a super balance of $400,000. Sam wants to reduce her work hours to four days a week while maintaining her lifestyle. This would mean a 20% drop in salary—down to $80,000.
- Sam opens a CSCri Transition to retirement (TTR) income stream and transfers $300,000 from her PSSap account to her TTR account.
- She starts receiving regular payments from her TTR account of $20,000 per year for five years - this supplements her reduced salary and keeps her total income steady at $100,000.
- Her TTR account is reduced by $20,000 a year for five years, reducing her account balance by approximately $100,000 by the time she turns 65.
Sam could have chosen to move more than $300,000 at the outset of setting up her TTR account as she only needs enough money in her PSSap account to cover her insurance premiums and to continue to receive super contributions made by her employer. Everyone’s circumstances are different. Consider talking to a CSC Super Specialist or seeking advice from a financial planner before deciding.
By using a TTR strategy:
- Sam works four days a week and earns $80,000.
- She receives $20,000 tax-free (because she’s over 60) from her TTR account.
- Her employer continues to make super contributions based on her reduced salary.
- Over five years, Sam reduces her overall super balance by approximately $100,000 meaning she has less super once she fully retires.
By using a TTR strategy, Sam is working less and living more. She uses her day off to look after herself and create content for her YouTube channel.
This case study is for illustrative purposes only and does not constitute financial advice. Individual circumstances vary. Consider seeking professional advice before making any decisions.
Need support?
Frequently asked questions
Who can open a TTR account?
You can open a TTR account if:
- you’re aged 60 to 64
- you’re still working (full-time, part-time or casual)
- you have at least $20,000 to transfer.
Is there a maximum I can transfer into a TTR account?
There is no maximum you can transfer into a TTR account. But the minimum (4%) and maximum (10%) annual withdrawal rates apply to the balance.
What happens when I turn 65?
Your TTR account will be automatically converted to a CSCri Standard retirement income account. No tax applies to investment earnings in retirement phase if your total super balance is less than $3.0 million*.
Your Transfer Balance Cap will apply. If you exceed the cap, the excess must be moved back to an accumulation account, such as your PSSap account, or withdrawn.
*The transfer balance cap limits the total amount of superannuation that can be transferred into a standard retirement income stream account. The general transfer balance cap is currently $2.1 million from 1 July 2026, although your personal transfer balance cap may differ depending on your circumstances.
In addition, from 1 July 2026, Division 296 tax applies to certain super earnings attributable to your total super balance if your total super balance is above $3 million. That is, an additional 15% tax applies to the proportion of earnings attributable to balances between $3 million and $10 million and an additional 25% tax applies to the proportion of earnings attributable to balances above $10 million. The tax applies only to the relevant proportion of earnings and not to the entire super balance.
For further information, refer to the Division 296 tax on large super balances information available on the ATO website.
Tax treatment depends on individual circumstances and may change in the future. Seek independent tax advice if you are unsure how the rules apply to you.
How do withdrawals work?
Lump sums
Generally, you can’t withdraw your super as a lump sum from a TTR account while still working - payments are made as regular income e.g. on a fortnightly, monthly, quarterly, half-yearly or yearly basis.
Withdrawal limits
You must withdraw at least 4% and no more than 10% of your TTR account balance each financial year. TTR income stream payments are tax-free for people aged 60 or over.
Will I still have my PSSap account?
Yes. If you transfer only part of your balance to TTR, your PSSap account stays open to:
- receive employer and personal contributions (and rollovers)
- deduct insurance premiums (if applicable)
Can I make contributions to my TTR account?
You can only make a one-off contribution to your TTR account when you first set it up. Contributions cannot be paid directly into an existing TTR account.
If you want to add more to your TTR account, you’ll need to re-start it with a minimum $10,000 additional contribution.
Find out more about re-starting a CSCri account.
What about my insurance cover?
Apply online
If you’re ready, you can apply online for a CSCri Transition to retirement income stream.
Before making a decision, make sure you’ve read the Product Disclosure Statement (PDS) and Target Market Determination (TMD).
Before acting on this information, consider your personal circumstances and seek advice where appropriate.
How to apply
-
Gather your information
You’ll need:
- your CSC member number (found in CSC Navigator or on your annual statement)
- Tax File Number
- the amount you’ll transfer to start your TTR account e.g. from your existing PSSap account, other super funds or personal contributions
- your investment option(s)
- bank account details to receive payments
- identity documents for digital verification, or certified copies e.g. your passport and driver licence
- beneficiary nomination
-
Complete your application
Complete the application and send it to us. You can start your application online by logging into CSC Navigator or download a PDF version. If you need assistance, contact 1300 736 096.
-
Consolidate your funds
Based on your application, your funds will be consolidated into your PSSap account (or a PSSap Ancillary account will be set up for you if you don’t already have one).
-
Your CSCri account will be set up
Once your information and funds are received and your application is accepted, your account is generally set up in around three business days.
-
Welcome to CSCri
You’ll receive a welcome email or letter with your CSCri account details. You’ll also be able to view all your CSC accounts, including your PSSap account (if applicable), online by logging into CSC Navigator.
Stories from CSCri members Gerard's story
Explore our Retirement guides and workbook
Our downloadable Retirement guides and workbook consider your retirement planning concerns and challenges. Learn moreFinancial planning
Get step-by-step advice designed to grow you a secure and stable future.
Learn moreHow much is enough?
Retirement is as individual as you are. Lifestyle, hobbies, family situation, health and existing assets play a big role in determining how much money you will need. Our short video and tools will show you how to tackle this important question.