Member and employer contributions
Understand how your defined benefit super grows, including member and employer contributions.
In a Defined Benefit fund, the amount you get—your Retirement Benefit—is determined by your fund's rules and is usually calculated using a formula based on:
- contributions made by your employer and contributions made by you (including any additional contributions, if applicable),
- your length of employment with the employer, and
- your Final Average Salary (FAS) when you retire (FAS is not applicable to CSS members).
Fund rules differ
Select your fund to view the details
- CSS
- DFRDB
- MilitarySuper
- PSS
This section contains:
Two types of contributions are paid regularly into PSS—member contributions and productivity contributions.
The remainder of your defined benefit is made up of fund earnings on those contributions and an employer component, which is derived from a formula.
Member contributions
Quick notes
As a contributing PSS member, you are required to pay fortnightly member contributions each fortnight from your after-tax salary.
These calculations are calculated as a percentage of your fortnightly super salary, and may be pro-rated if you are a part-time employee.
Your contribution rate can be 0%, or any whole percentage between 2% and 10%. This means 1% is not permitted, and neither is any partial percent like 6.5%. If you don’t nominate a contribution rate, you will be defaulted to a rate of 5%.
The details
- Member contributions are always rounded to the nearest cent.
- They are payable on every Contribution Due Day (CDD), which are fortnightly, every second Thursday, in line with APS pay periods.
- Member contributions are paid by your employer, from your after-tax income.
- You are only due to pay contributions while you are a contributing member.
- You are only a contributing member up until your last day of employment with an eligible employer (e.g. your government agency). Depending on when you cease eligible employment, there may be salary owing to you on a payday after you have finished. As you are no longer a contributing member on that future payday, no contribution is due or payable on that day.
ExamplesRounding Nadija has a super salary of $100,000. Her contribution rate is 5% and she is a full-time employee. Her fortnightly super salary is $3,846.15 ($100,000 / 26). Nadija’s fortnightly member contribution is $192.31 ($3,846.15 x 5%). Future payday Kevin ceased ‘eligible employment’ on Friday 15 September 2023. He would likely have received a salary payment on Thursday 28 September 2023, but contributions would not have been due or payable on this date as Kevin was not a contributing member at that time. |
Age restrictions
We cannot accept contributions for you if you are 75 years or older.
Changing your contribution rate
You can change your contribution rate as often as you like by notifying your employer, as it is your employer’s responsibility to withhold these contributions and pay them to CSC. Any changes will apply from the next applicable CDD.
Employer Contributions
Productivity
Quick notes
Employer Productivity Super Contributions (known as ‘EPSC’ or 'productivity contributions') are regular employer contributions paid into your account based on your super salary.
Your employer pays productivity contributions on any CDD that a member contribution is due (even if you have elected a 0% member contribution rate).
We withhold 15% contributions tax on entry to the fund.
The details
- The rate at which productivity is paid depends on the member's super salary. The thresholds that determine the rate are indexed each financial year.
- When calculating your benefit, we only consider the productivity due, so you are not disadvantaged if an employer fails to pay productivity on your behalf.
- Member and funded productivity contributions are invested and attract earnings from the time they are paid into and received by the fund.
Did you switch from CSS to PSS?
You may have ‘unfunded’ productivity contributions in your benefit if you elected to switch from CSS to PSS and have had your CSS membership subsumed with your PSS membership.These were contributions relating to the period 1 January 1988 to 30 June 1990.
While due (and therefore included in the benefit), they were never (and will not be) paid into the fund, hence the name 'unfunded'. Because they were never actually paid, notional earnings are attributed to them at the fund earning rate. These earnings are also treated as unfunded amounts.
Unfunded productivity is included in the overall productivity component.
Employer benefit
The contribution rate impacts one of the factors in the formula used to calculate the final PSS benefit, in turn affecting the growth rate of your defined benefit:
Defined Benefit Accrual = FAS x ABM
Where FAS = Final Average Salary & ABM = Accrued Benefit Multiple.
Final average super salary
Final Average Salary (FAS) is typically the average of your last three reported birthday super salaries.
Annual ABM accrual
ABM is often presented using the following table. This is a simplified illustration based on a number of assumptions including full-time employment and 26 (CDDs) in a year.|
Rate |
Annual ABM accrual |
Annual ABM accrual (ten-year rule satisfied) |
|
0% |
0.11 |
0.11 |
|
2% |
0.15 |
0.15 |
|
3% |
0.17 |
0.17 |
|
4% |
0.19 |
0.19 |
|
5% |
0.21 |
0.21 |
|
6% |
0.22 |
0.23 |
|
7% |
0.23 |
0.25 |
|
8% |
0.24 |
0.27 |
|
9% |
0.25 |
0.29 |
|
10% |
0.26 |
0.31 |
Your contribution rate affects the growth of your defined benefit accrual. For a member contributing to PSS at 5% on a full-time basis, the annual ABM accrual is calculated as: 0.11 + (2 x contribution rate).
ExampleLouise contributing at a rate of 5% for a year. Her ABM accrual for that period is 0.11 + (2 x 5%) = 0.21 |
Fortnightly ABM accrual
In reality, ABM accrual does not occur on an annual basis. The annual accrual rate is divided by 26 to determine the fortnightly accrual.
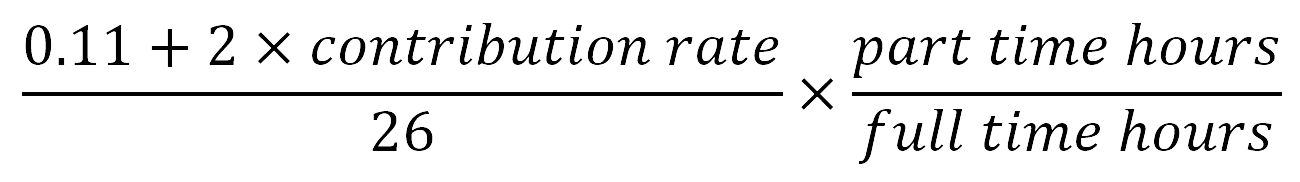
Note: If there are 27 CDDs in a year, members will receive an additional fortnight's accrual, but each fortnightly accrual is calculated as 1/26th of the relevant annual amount.
The ‘ten-year rule’ restricts the rate at which the ABM grows. For 10 years or 260 CDDs, the permitted ABM accrues as if the member had contributed at up to 5%. Once a member has contributed for more than 260 CDDs, the ABM accrual will reflect the actual rate of member contributions up to 10%. This rule therefore only affects members who elect a contribution rate of more than 5%.
The 260 CDDs or 10 years do not have to be a continuous period, nor do they have to be the first 10 years of membership. The actual calculation of the ’10-year rule’ is performed at the time a member claims their benefit or a benefit multiple is calculated.
Your final benefit
The formula Final Average Salary (FAS) x Accrued Benefit Multiple (ABM) determines the Defined Benefit Accrual, but it is actually made up of three components—member, productivity and employer.
The member and productivity components are determined by the accumulated contributions paid (by you) or due (from your employer). The employer component makes up the difference.
In other words:
-
Employer component = FAS x ABM - (member component + productivity component)
or
-
FAS x ABM = member component + productivity component + employer component
Maximum benefit limit (MBL)
There is a limit to the Defined Benefit that you can accrue as a contributing member. This is called the Maximum Benefit Limit (MBL).
Depending on your Final Average Salary (FAS), your MBL will either be a dollar amount or a multiple of your average salary. MBL thresholds are adjusted in line with Average Weekly Ordinary Time Earnings (AWOTE)2 on 1 July each year.
- How long it takes you to reach your MBL primarily depends on your contribution rate and how long you've been a member.
- If you reach your MBL, you won't be permitted to make contributions to PSS, even if your salary increases further.
- Instead, you might consider making contributions to a personal accumulation account with PSSap or another fund of your choice.
We monitor the records of all members who are approaching their MBL and attempt to notify you when you reach it. If this happens, your employer will stop making both member and productivity contributions, and super salary will continue to be reported to us until you cease eligible employment.
Your final benefit will be calculated based on your FAS at the time you claim, not the FAS in effect when you reached your MBL. Reaching your MBL means your Defined Benefit amount will either be the MBL in effect at the time you claim, or 10 times your current FAS, depending where your FAS sits on the MBL threshold table.
You should contact us for more specific information if you:
- reached your MBL before 1 January 2008 on a current or a previous PSS membership,
- have received or are entitled to receive an adjustment payment under the Australian Federal Police Act 1979, or
- would like to know more about how your MBL may affect your death or invalidity benefits.
2AWOTE is a measure of average earnings in Australia at a particular point in time, published twice a year by the Australian Bureau of Statistics.
Maximum Benefit Limits 2026–27
| Average Salary | Maximum Benefit |
|---|---|
| Less than $97,000.00 | $970,000.00 |
| $97,000.00 and over | 10 times average salary |
Your transfer amounts that become payable after 31 December 1995 and government contributions are not counted towards your MBL. Transfer amounts that became payable on or before that date will count towards your MBL.
ExampleBruce’s average super salary is $71,000. This means his MBL is $970,000. Assuming Bruce’s super salary doesn’t change, he’ll reach his MBL when his ABM is 13.66197 ($970,000 ÷ $71,000). |
ExampleDonna’s average super salary is $90,000, so her MBL is $970,000. She’ll reach her MBL when her ABM is 10.77777. If her average super salary increases to $98,000 while she is contributing, Donna’s MBL will increase to $980,000 (10 x $98,000). |
Reaching your MBL
Your MBL can be calculated using the method above. You can compare your current ABM with the MBL applicable to your current average super salary to estimate if—or when—you’ll reach your MBL. As a guide, the table below shows the annual ABM accrual for different contribution rates.
As a guide, the table below shows the annual ABM accrual for different contribution rates. You can multiply your average super salary by your ABM to calculate your defined benefit amount. Remember to allow for any periods of leave without pay that don’t count as service, as your ABM doesn’t accrue then.
| Contribution rate | Annual ABM (first 260 CDDs)* | Annual ABM (Ten year rule satisfied)* |
|---|---|---|
| 0% | 0.11 | 0.11 |
| 2% | 0.15 | 0.15 |
| 3% | 0.17 | 0.17 |
| 4% | 0.19 | 0.19 |
| 5% | 0.21 | 0.21 |
| 6% | 0.22 | 0.23 |
| 7% | 0.23 | 0.25 |
| 8% | 0.24 | 0.27 |
| 9% | 0.25 | 0.29 |
| 10% | 0.26 | 0.31 |
*The ten year rule refers to members who have contributed to PSS for 260 public service pay days or contribution due days (CDDs)—the equivalent of ten years’ continuous employment. After the first 260 CDDs, if your contribution rate is more than 5%, your ABM accrues at a higher rate.
The MBL relates to your total defined benefit. If you’ve had your benefit reduced as a result of a family law settlement, your MBL still refers to your unreduced benefit. The same applies if you’ve claimed an early release of your super.
Associate benefits are not impacted by MBLs.
ExampleBruce’s MBL is $970,000 or an ABM of 13.66197 (based on an average super salary of $71,000). His last statement indicated his ABM was 9.85. He is currently contributing to PSS at a rate of 10% of his super salary, so his ABM is growing by 0.31 per year (based on full-time employment). If Bruce continues to contribute at this rate, it will take him less than 13 years to reach his ABM of 13.09859. However, Bruce should review his situation each July, as the PSS MBL thresholds are adjusted each financial year. |
What happens if you reach your MBL
Once you reach your MBL, you won’t be able to make contributions to PSS, even if your salary increases further. Instead, you may choose to make contributions to a PSSap ancillary account or another fund of your choice. You should note that this won’t allow your employer to make contributions on your behalf.
We monitor the records of all members who are approaching their MBL and we’ll notify your employer when you reach it. They’ll stop making member contributions on your behalf, and no longer pay productivity contributions. Your super salary will continue being reported to us each birthday until you cease eligible employment.
How the MBL affects your benefit
Your final defined benefit amount will depend on your FAS when you claim your benefit, not when you reach your MBL. Reaching your MBL will mean your defined benefit amount is either the MBL in effect at that time, or 10 times your FAS, depending whether your FAS is below or above the threshold.
If you reached your MBL during a previous membership
If you reached your MBL during a previous period of membership, you’ll remain an MBL member for any new periods of membership. This means you won’t be able to contribute to your PSS membership, and your employer won’t pay productivity contributions. Your benefit will continue to grow in line with salary increases. Instead, you may like to consider contributing to a PSS accumulation plan account or another fund of your choice, separate to your PSS benefit.
You may also have the option to cease PSS membership (opt out) and join PSSap* or your employer’s default fund. PSSap membership would allow your employer to pay 15.4% of your super salary** as employer contributions.
For more information about opting out of PSS, please refer to Ceasing PSS membership.
*You should contact your employer to check if you’re eligible for PSSap membership. As a PSSap member you may be eligible to join another fund of your choice.
**Depending on the terms of your employment, employer contributions to PSSap may be based on your Ordinary Time Earnings.
If you're a former CSS member
If you’re a former CSS member, your ABM will include a CSS transfer multiple. This multiple will be counted towards your MBL.
Employer liability
In addition to productivity, your employer pays another contribution to CSC in the form of employer liability contributions (sometimes referred to as 'Employer Super Contributions' or ESC). These are paid into the Consolidated Revenue Fund and do not affect your benefit calculation, but you may see these contributions on your payslips.
Concessional contributions
Quick notes
If you are considering salary sacrificing into another super fund, you need to take into account the concessional contributions cap.
Concessional contributions are contributions that are paid into the fund before tax, and tax is withheld at 15% on entry. The general concessional cap is $32,500 for the 2026–2027 financial year; however, you may have a larger personal cap by using the 'carry-forward' rule.
To be eligible for the carry-forward rule, you must have a Total Super Balance (TSB) of less than $500,000.
To find out about your eligibility, contact the ATO.
The details
- If your Total Super Balance (TSB) is less than $500,000, you can access your unused concessional cap space on a rolling basis for 5 years. Amounts carried forward that have not been used after five years will expire.
- If you exceed your personal concessional cap, you may be liable to pay additional tax.
If you joined PSS prior to 12 May 2009 and your Defined Benefit Contributions (DBC) exceed the concessional cap, grandfathering rules may apply. This means you may not exceed the concessional cap solely due to these contributions. More information is available from the ATO here.
Open a personal accumulation account
Opening an accumulation account may give you access to more flexible contribution and investment options.